When the quantity surveyor prices the job higher than the borrower did

Light Refurbishment
A mixed-use block needing £75k of work, until the surveyor said otherwise. We funded the real number.
Location: Nuneaton, Warwickshire
Property: Mixed use — retail unit, self-contained flats and letting rooms
Purchase Price: £200k
Valuation: £225k
Gross development value: £385k
Day one loan: £150k
Refurbishment facility: £100k
Total facility: £250k
Loan to gross development value: 75% gross, including fees and interest
Term: 12 months, interest rolled
Exit: Refinance onto a term loan
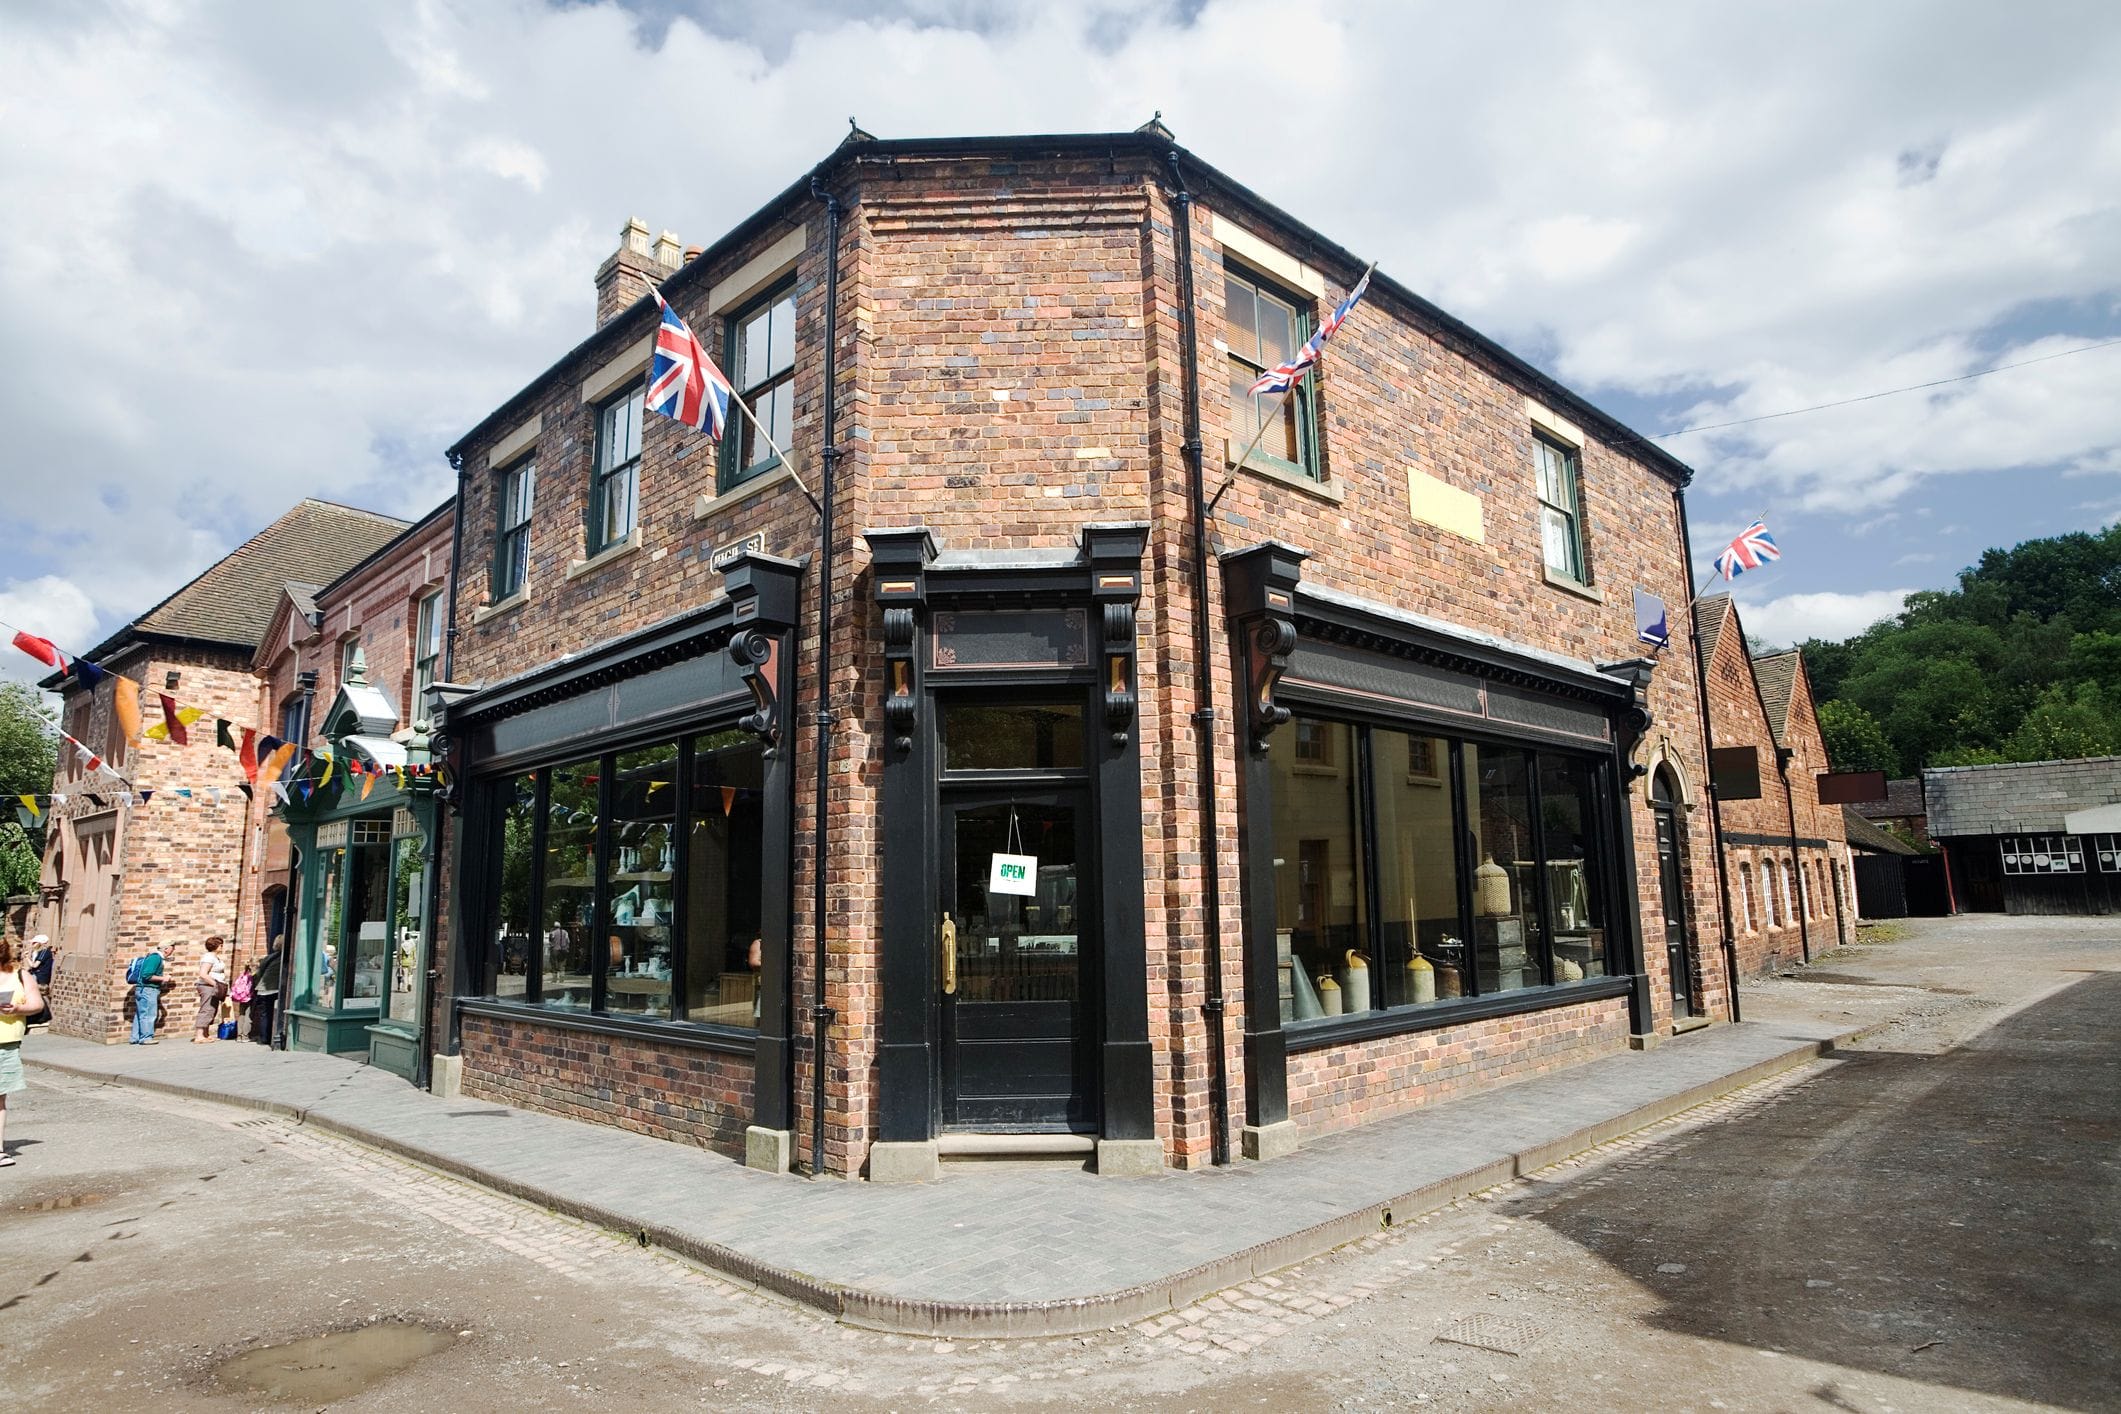
A single-director company came to us to buy a mixed-use block: a retail unit and a one bedroom flat at ground level, with three letting rooms and a studio flat above. The plan was a straightforward internal refurbishment — kitchens, bathrooms, flooring and decoration — with no change to the layout and no planning required. The borrower had costed the works at around £75k.

The surveyor disagreed, and that was useful
Our monitoring surveyor priced the same schedule at £100k — a third higher than the borrower’s estimate. That is exactly what the initial report is for. A borrower who starts a refurbishment £25k short does not finish it, and a lender who funds the optimistic figure ends up with a half-finished building. We funded the surveyor’s number instead, drawn in arrears against inspection as the work completed.
A credit score that needed reading properly
The director’s headline credit score came back at 660 — flagged as high risk by the bureau. Rather than decline on the number, we asked for a full multi-agency report. It showed clean conduct across every account. The score reflected a thin file rather than anything adverse, and the borrower — a construction site manager by trade — had already bought, refurbished and let a property of his own, adding around £40k of value in the process. Experience and evidence beat a headline score.
Why it worked
- An initial surveyor’s report that corrected the cost plan before work started, not after.
- Insight A borrower whose day job and previous project matched what he was proposing to do.
- A full valuation and monitoring surveyor throughout, with funds released against inspection.
Recent Case Studies
 View all Case Studies

£556,000 raised against land with planning
£556,000 raised against land with planning Bridging - Land with planning Shropshire · Where neither [...]

Four stone barns, and a planning permission worth protecting
Four stone barns, and a planning permission worth protecting Development A £1.46m facility on a barn [...]

Three bedrooms in, six en-suite rooms out
Three bedrooms in, six en-suite rooms out Heavy Refurbishment A house in multiple occupation conversion funded [...]

A first investment purchase, bought under the hammer
A first investment purchase, bought under the hammer Residential Bridge Two first-time investors found a [...]
Need to speak to an expert?
Got a deal that needs a conversation? Bring us the detail and we’ll tell you whether it looks like one for Breeze.