A first investment purchase, bought under the hammer

Residential Bridge
Two first-time investors found a property £55k below its value. Their day jobs meant most lenders wouldn’t look at them.
Location: Folkestone, Kent
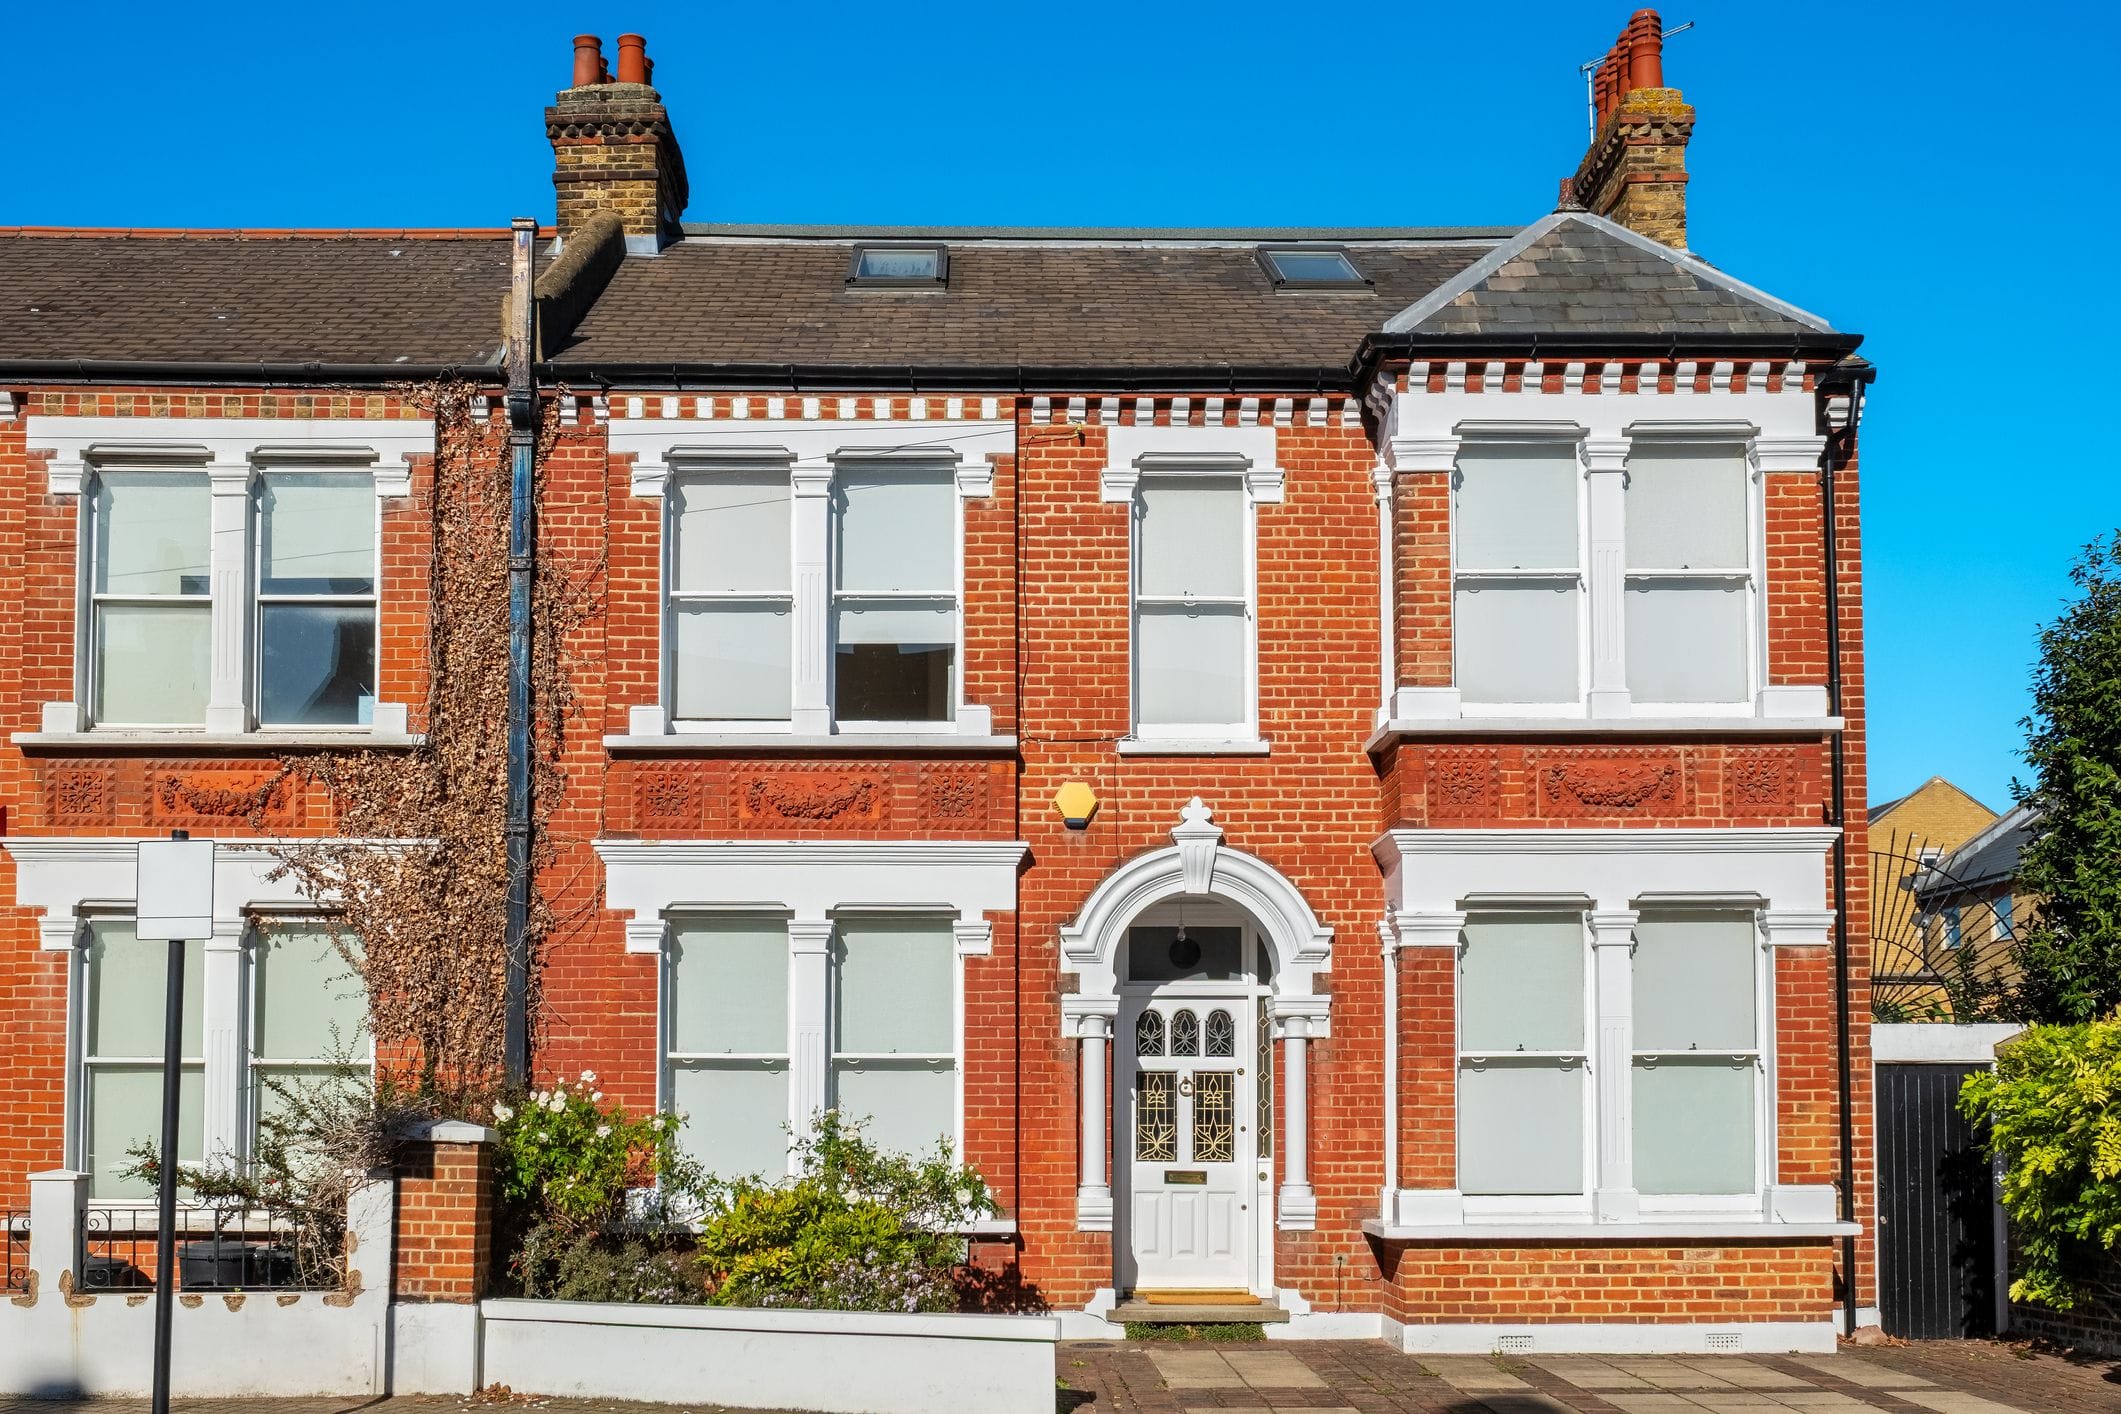
Property: Three bedroom mid-terrace house, freehold
Purchase Price: £160k
Valuation: £215k
Day one loan: £152k
Loan to value: 71% of valuation
Term: 12 months, interest serviced
Exit: Refinance onto a term loan
A couple buying their first investment property through a limited company came to us via their broker. The property had been listed by modern method of auction after a previous sale collapsed for reasons unconnected with the property, and they had secured it at £160k against a valuation of £215k.
On paper they were a difficult case. Neither is a full-time investor — one works as an administrator, the other in sales — and combined earned salaries were modest. Several lenders would have stopped there.

What we looked at instead
They owned their own home, had clean credit with no defaults or judgments between them, and had raised their contribution against their own property. The security was a straightforward freehold terrace in an established residential area with a clear rental market.
Most importantly, they had bought well. We size a purchase against the valuation rather than the price, so the £55k of value they had negotiated worked for them rather than being ignored.
At £152k the loan sat at 71% of the valuation, with the borrowers contributing the balance of the purchase price from their own funds.
Getting it done
The case ran on a dual representation basis with title insurance in place, which allowed limited legal due diligence rather than a full title investigation, and took several weeks out of the timetable.
Interest was serviced monthly rather than rolled, keeping the redemption figure tight and making the refinance exit easier to evidence. The borrowers expect a rental income of around £1,400 a month, comfortably supporting a term loan at the end of the bridge.
Why it worked
- A genuine discount, evidenced by a full RICS valuation rather than an estimate.
- Borrowers who owned property already and had clean credit behind them.
- A simple security in a location with a proven rental market.
- Insight Title insurance and dual representation to compress the legal timetable.
Recent Case Studies
 View all Case Studies

£556,000 raised against land with planning
£556,000 raised against land with planning Bridging - Land with planning Shropshire · Where neither [...]

Four stone barns, and a planning permission worth protecting
Four stone barns, and a planning permission worth protecting Development A £1.46m facility on a barn [...]

Three bedrooms in, six en-suite rooms out
Three bedrooms in, six en-suite rooms out Heavy Refurbishment A house in multiple occupation conversion funded [...]

When the quantity surveyor prices the job higher than the borrower did
When the quantity surveyor prices the job higher than the borrower did Light Refurbishment A mixed-use [...]
Need to speak to an expert?
Got a deal that needs a conversation? Bring us the detail and we’ll tell you whether it looks like one for Breeze.