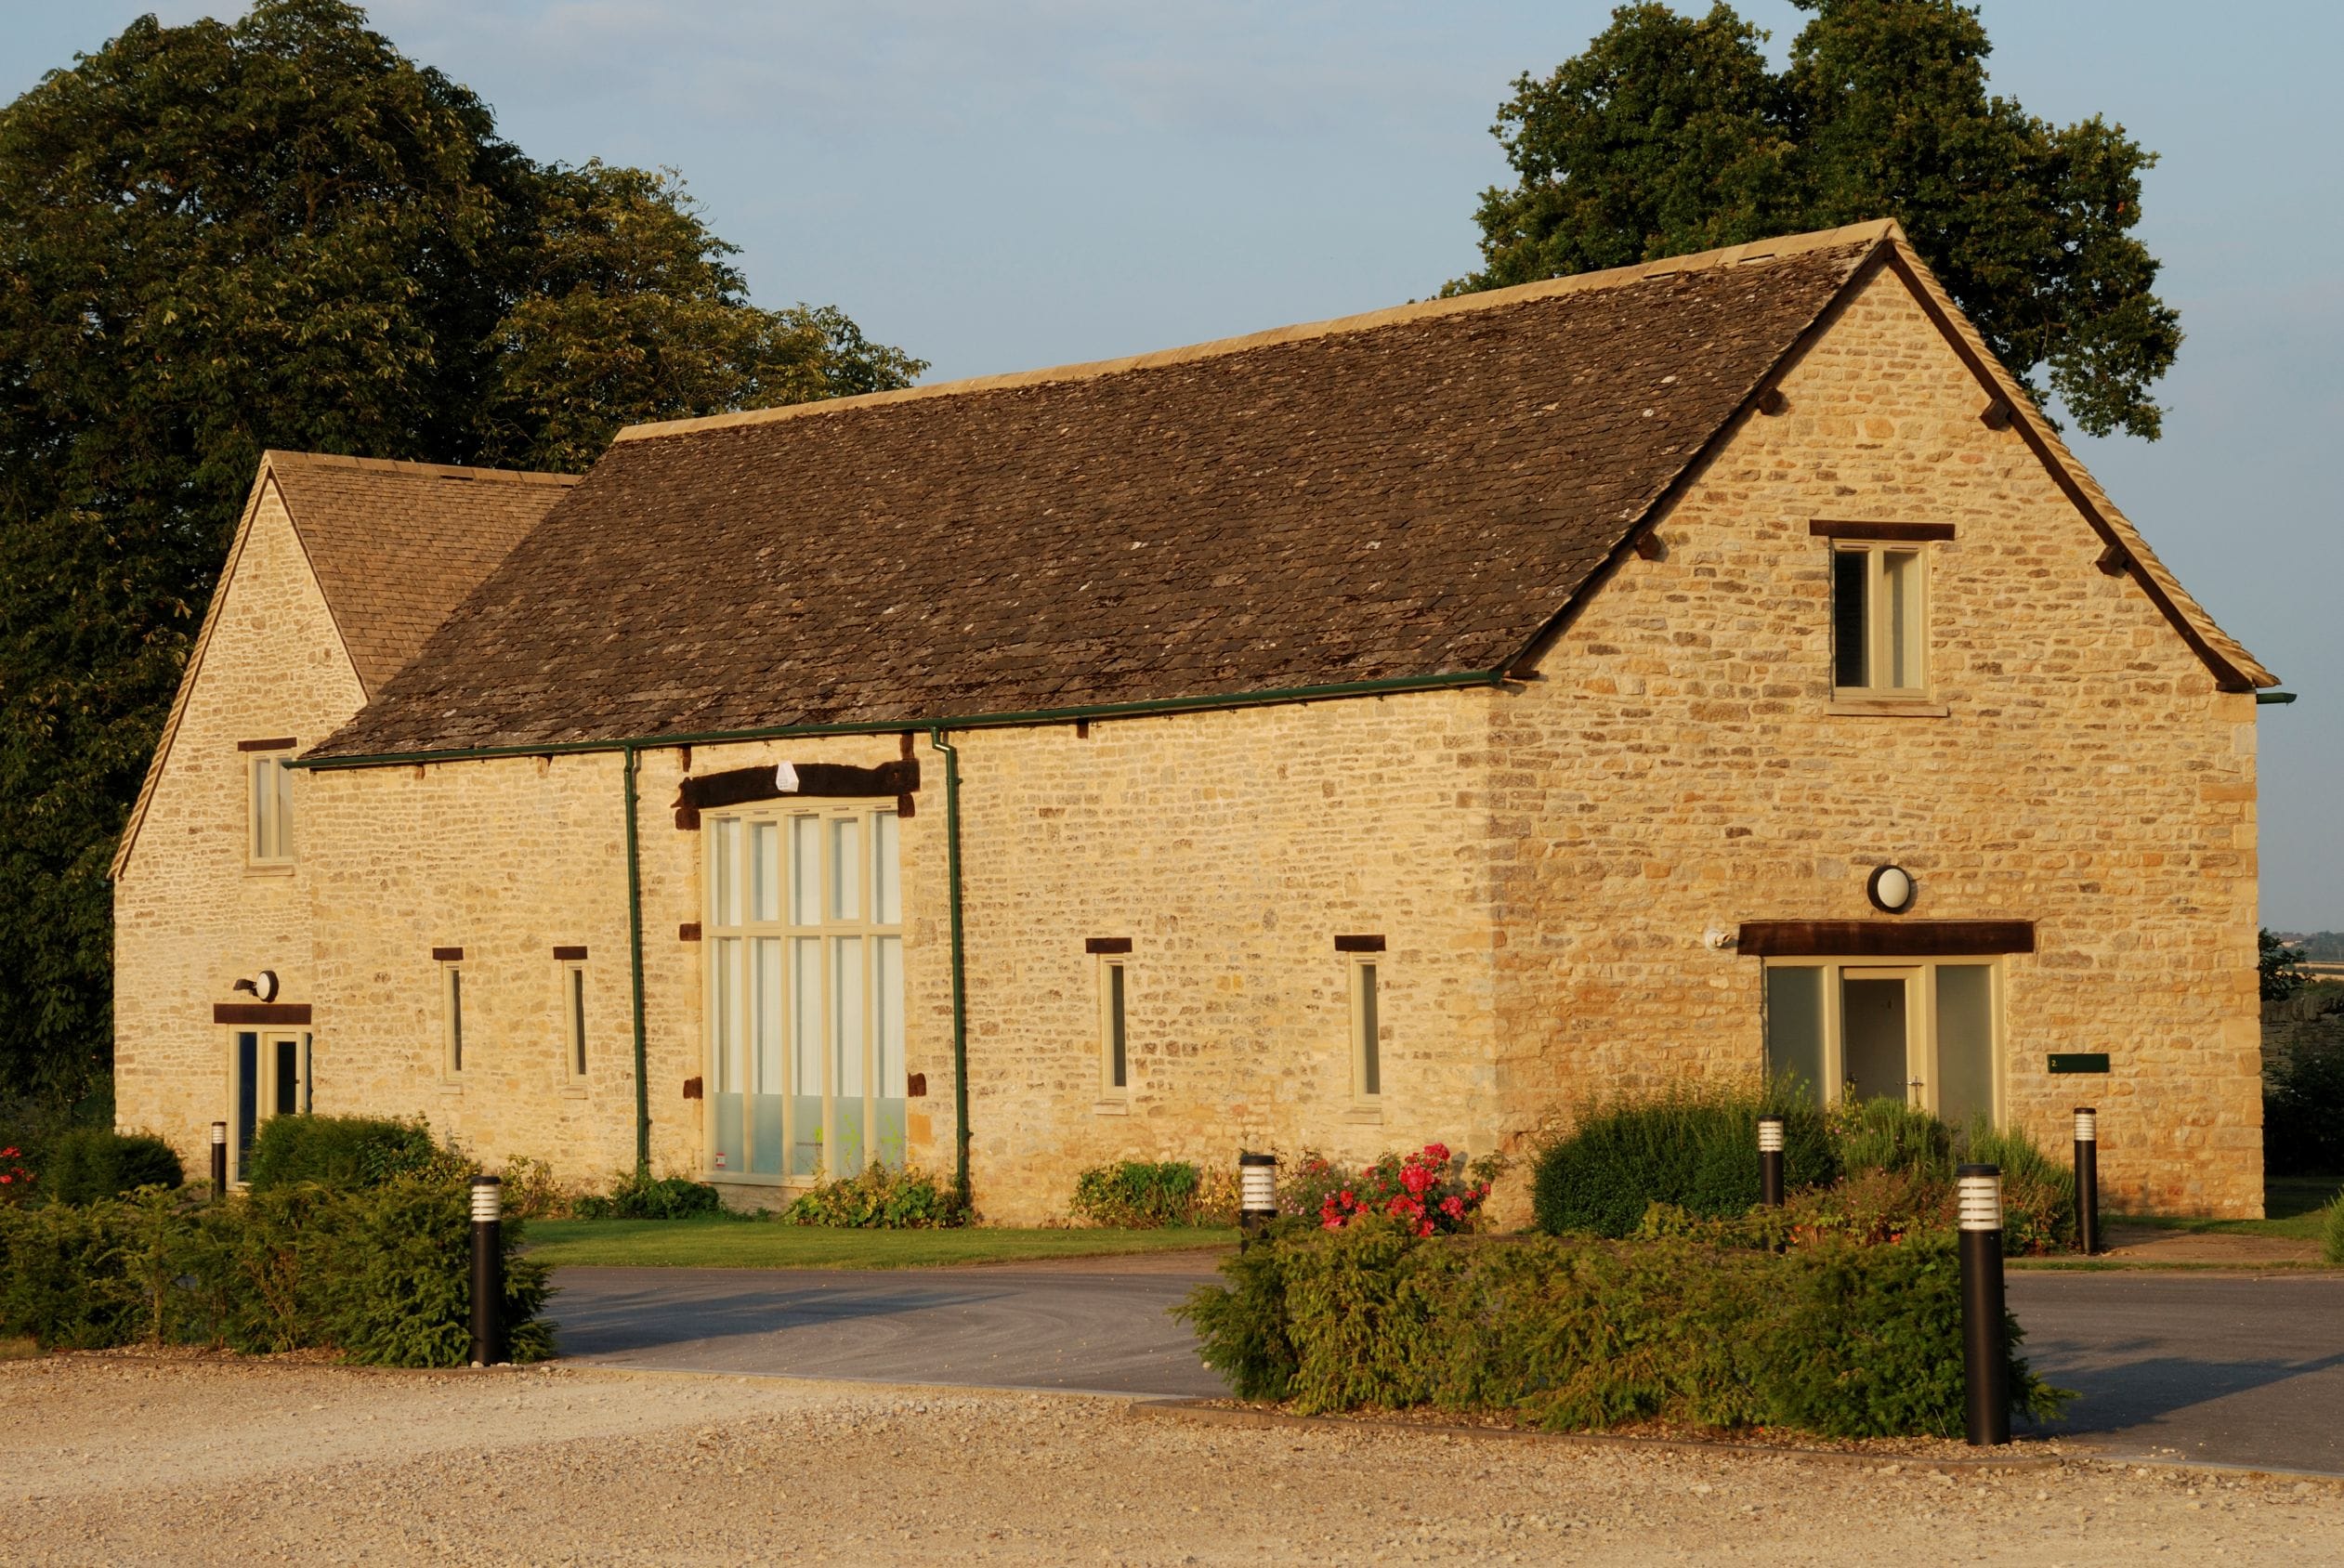
Four stone barns, and a planning permission worth protecting

Development
A £1.46m facility on a barn conversion where twelve months of planning work had to be preserved before we could lend.
Location: Slyne, near Lancaster
Property: Four traditional stone barns, converting to three and four bedroom homes
Purchase Price: £313k
Valuation: £380k
Gross development value: £2.56m
Day one loan: £205k
Development facility: £1.25m
Total facility: £1.46m
Loan to gross development value: 69% gross, including fees and interest
Term: 15 months, interest rolled
Exit: Sale of the completed properties
Two directors with a twenty year working partnership in construction approached us directly to fund the purchase and conversion of four traditional stone barns into family homes, with full planning consent already in place.
Between them they brought forty years of managing construction companies, including principal contractor roles — the sort of borrower who has run projects considerably more complicated than this one.

The planning had to survive completion
The consent carried pre-commencement conditions, and the borrower had spent the previous twelve months discharging them. The permission had a hard expiry date, and it had to be lawfully implemented before it ran out — otherwise the whole scheme fell away.
This is the point at which a lot of barn and conversion schemes come unstuck. A permission implemented without every pre-commencement condition discharged first may not be valid at all, and that tends to be discovered far too late.
We worked through the position with the borrower and their solicitor before completion, confirming the works already carried out on site were sufficient to commence the development lawfully, and that every condition had been signed off first.
Funding the scheme
£205k on day one against a site valued at £380k and the full £1.25m of development costs held and released in arrears against a monitoring surveyor’s inspections.
Personal guarantees were limited to 30% of the outstanding facility — reflecting the directors’ track record and the equity they hold personally. Third party investors funding the deposit and cashflow took no charge, and their funds were subordinated to ours by deed.
At £1.46m the total facility sat at 69% of a £2.56m gross development value, with the exit coming from the sale of the completed homes.
Why it worked
- Detailed planning already granted, with every pre-commencement condition discharged.
- Borrowers who were also the contractors, with forty years behind them.
- Development costs funded in full, released against inspection.
- Third party investor funds subordinated, so our charge ranked clear.
Recent Case Studies
 View all Case Studies

£556,000 raised against land with planning
£556,000 raised against land with planning Bridging - Land with planning Shropshire · Where neither [...]

Three bedrooms in, six en-suite rooms out
Three bedrooms in, six en-suite rooms out Heavy Refurbishment A house in multiple occupation conversion funded [...]

A first investment purchase, bought under the hammer
A first investment purchase, bought under the hammer Residential Bridge Two first-time investors found a [...]

When the quantity surveyor prices the job higher than the borrower did
When the quantity surveyor prices the job higher than the borrower did Light Refurbishment A mixed-use [...]
Need to speak to an expert?
Got a deal that needs a conversation? Bring us the detail and we’ll tell you whether it looks like one for Breeze.